Market overview and structural significance of the Collagen Pet Supplement Market
Our analysis indicates that the Collagen Pet Supplement Market represents a rapidly expanding category within veterinary nutraceuticals, valued at $1.13 Billion in 2026. This sector encompasses specialized formulations derived from marine, bovine, and chicken sources designed to enhance longevity and mobility in domestic animals.
Structural Growth Drivers, Restraints, Challenges, and Opportunities
The market is propelled by the rising trend of humanization of pets and escalating veterinary healthcare expenditures. Regulatory hurdles from agencies like the FDA-CVM and AAFCO present compliance challenges, yet immense opportunities persist within functional snack formats and preventative geriatric care regimens.
Emerging Industry Trends and Formulation Innovations
Formulators are increasingly pivoting toward clean-label, plant-based collagen boosters alongside advanced marine hydrolysates. Bioavailability enhancement remains a primary focus, leveraging enzymatic hydrolysis to improve absorption rates in feline and canine digestive tracts.
COVID-19 Pandemic Impact and Post-Crisis Recovery Trajectory
The pandemic accelerated pet adoption rates and heightened owner vigilance regarding animal wellness. Supply chain bottlenecks for raw gelatin and transport delays through major logistics hubs temporarily disrupted production, but robust e-commerce channels fueled a swift recovery.
Competitive Benchmarking and Market Concentration
The Collagen Pet Supplement Market features a blend of established animal health giants and agile direct-to-consumer innovators. Market concentration is moderately fragmented, with leaders leveraging proprietary peptide technologies and targeted veterinary endorsements to capture market share.
Executive Summary: High-Level Synthesis of Proprietary Findings
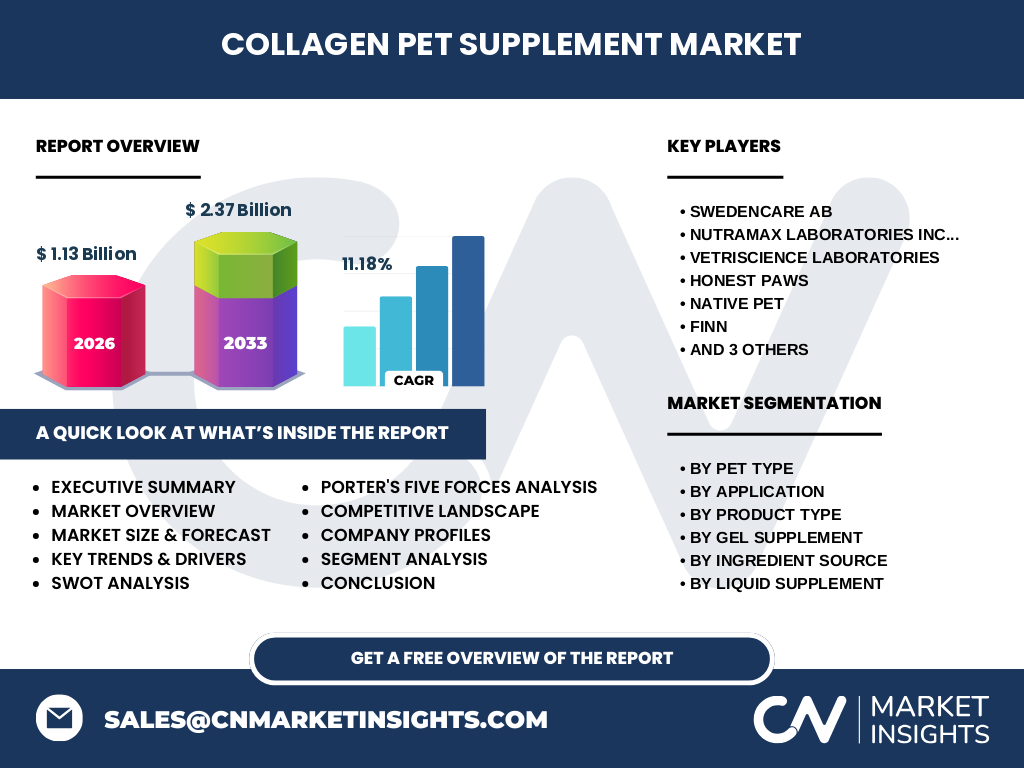
Our research forecasts the market to expand from $1.13 Billion in 2026 to $2.37 Billion by 2033 at a CAGR of 11.18%. Growth is heavily concentrated in joint health and specialized skin-and-coat applications distributed primarily through online channels and veterinary clinics.
Long-Term Market Forecast from 2027 to 2033
Driven by persistent demand for preventive veterinary care, the market is projected to achieve a robust 11.18% CAGR, scaling from 2027 to reach $2.37 Billion by 2033. This trajectory reflects sustained consumer willingness to invest in premium pet longevity solutions.
Segmentation Analysis Across Pet Types, Applications, and Formats
The market segments comprehensively across pet types including Dog, Cat, Horse, Bird, and Small Animal. Applications span joint health, skin and coat, and bone support, delivered via powder, chewable, liquid, gel, and soft chew product formats.
Geographic Distribution and Regional Market Performance
Geographic performance highlights North America as the dominant revenue generator, underpinned by high pet insurance penetration. Meanwhile, Asia-Pacific emerges as the fastest-growing region due to rising disposable incomes and urban pet humanization trends across metropolitan centers.
In-Depth Regional Review and Localized Market Constraints
North American growth is anchored by advanced retail distribution networks, whereas European markets face stringent EFSA regulations regarding animal feed additives. APAC expansion requires navigating complex import tariffs for raw bovine and marine collagen inputs.
Strategic Positioning of Leading Industry Participants
Industry leaders such as Swedencare AB and Nutramax Laboratories Inc. anchor their strategies in veterinary-grade clinical backing. Meanwhile, digital-first brands like Honest Paws, Native Pet, and Finn capture millennial demographic loyalty via subscription-based e-commerce models.
Porter's Five Forces Assessment of Competitive Dynamics
Bargaining power of suppliers is moderate due to reliance on specific slaughterhouse and fisheries byproducts. Threat of substitutes remains low given collagen's unique amino acid profile, whereas competitive rivalry is intense among specialized brands like VetriScience Laboratories and Wholistic Pet Organics.
SWOT Analysis of the Collagen Pet Supplement Ecosystem
Key strengths lie in high product efficacy for mobility support, while weaknesses involve consumer skepticism over ingredient purity. Opportunities abound in equine and avian segments, with external threats stemming from raw material cost volatility.
Value Chain Analysis from Raw Material Sourcing to End-Users
The value chain initiates with agricultural and marine raw material extraction, progressing through enzymatic hydrolysis facilities, contract manufacturing plants, and final distribution via veterinary clinics, pet specialty stores, and digital storefronts.
Strategic Investment Insights and High-Potential Areas
Investors should target emerging formulators specializing in functional soft chews and targeted recovery gel supplements. Companies integrating transparent supply chains and third-party quality testing are positioned for superior valuation multiples.
Conclusion and Strategic Takeaways for Industry Stakeholders
Surpassing $2.37 Billion by 2033, the market rewards strategic investment in bioavailable formulations and omnichannel distribution. Brands must navigate evolving regulatory standards while capitalizing on shifting pet owner demographics toward preventative wellness.
Research Methodology and Baseline Triangulation Protocols
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with veterinary pharmacologists, and secondary macroeconomic indicators tracking global pet care expenditure growth.
Scope of the Report and Analytical Parameters
This report evaluates the global Collagen Pet Supplement Market across specified product formats, ingredient sources, and distribution channels from 2026 through 2033, excluding non-collagenous general vitamin matrices and livestock feed additives.
Recent Industry Developments, Partnerships, and Product Launches
Recent market activity features strategic acquisitions by legacy players and the launch of specialized veterinary prescription formulas by innovators like Petz Park and FLT Pet Products Inc., signaling heightened consolidation and premiumization across the sector.